

 Top

Federal Reserve Board
On October 28, the Federal Open Market Committee (FOMC) voted 10-2 to hold the target range for the federal funds rate at 3.75%-4.00%. Federal Reserve (Fed) Board Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favor of another 25 basis point increase. The Committee upgraded its assessment of economic activity from a solid pace to a strong pace, citing resilient domestic spending, robust capital investment and continued productivity growth. Chair Kevin Warsh acknowledged that September’s increase has begun to influence financial and credit conditions, but there is still room for additional tightening, and emphasized that inflation remains too high. With September consumer price index (CPI) inflation at 3.7% year-over-year1 and the labor market remaining resilient, the dissents and the Fed’s messaging suggest further rate increases. Warsh also announced that, beginning in 2027, one of the eight scheduled meetings will be dedicated exclusively to policy strategy and will not include a policy rate decision. In 2028, there will be two policy strategy meetings.
European Central Bank
On October 29, the European Central Bank (ECB) unanimously left the Deposit Rate unchanged at 2.50%. Higher oil and gas prices tied to the Middle East conflict pushed euro area inflation to 3.8% in September from 3.2% in August.2 The ECB noted that underlying inflation remains broadly stable and wages have yet to respond materially, but warned that the size and persistence of the energy shock raise the risk of second-round effects. The euro area economy has remained resilient, with continued expansion in the third quarter and a robust labor market, although tighter financing conditions and weaker consumer confidence pose downside risks to growth. Separately, President Lagarde announced that she will step down from her role on February 7, 2027, about eight months before her term ends. The Governing Council reiterated that decisions will remain data-dependent and meeting-by-meeting, with no pre-commitment to a rate path.
Bank of England
At its most recent meeting on September 17, the Bank of England’s Monetary Policy Committee (MPC) voted 6-3 to leave the Bank Rate unchanged at 3.75%, with three members preferring a 25 basis point increase to 4.00%. The MPC indicated that higher energy prices stemming from the Middle East conflict have increased upside risks to inflation, while evidence of second-round effects on wages and prices remains limited. Economic activity has been somewhat stronger than expected, with around 0.4% gross domestic product (GDP) growth projected for the third quarter, while labor market conditions remain soft.3 CPI inflation rose to 3.1% in August,4 and the official forecast expects it could exceed 4% in early 2027 before gradually moderating. The MPC also unanimously continued its balance sheet reduction, with a multi-year plan for gilt holdings to decline to zero at an average pace of £46 billion per year through 2034. Future decisions remain data-dependent, with a focus on inflation persistence, wages and geopolitical risks.
Monthly Interest Rate Summary
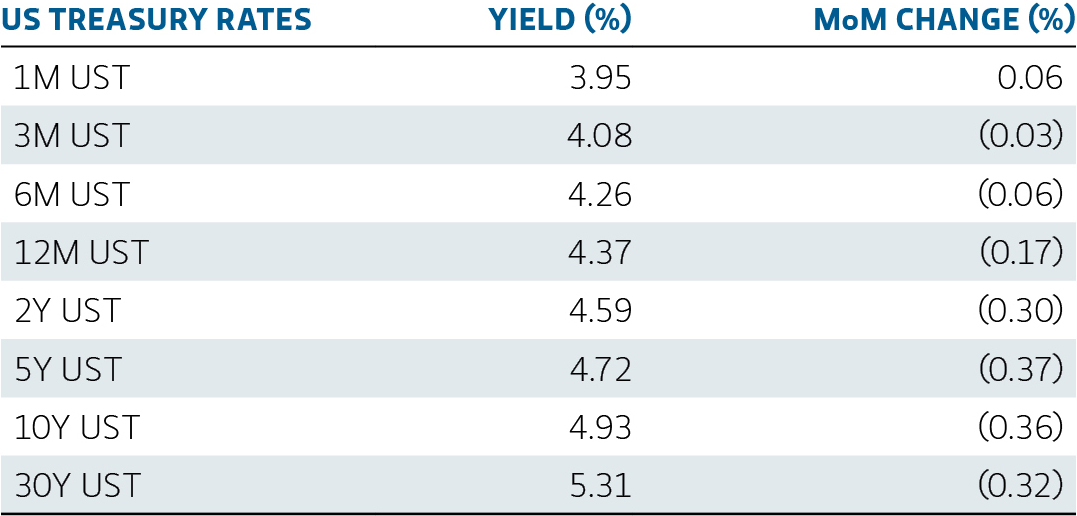
Source: Bloomberg
Monthly Interest Rate Summary
As of 10/31/26
MSILF Weighted Average Maturities (WAM) Summary
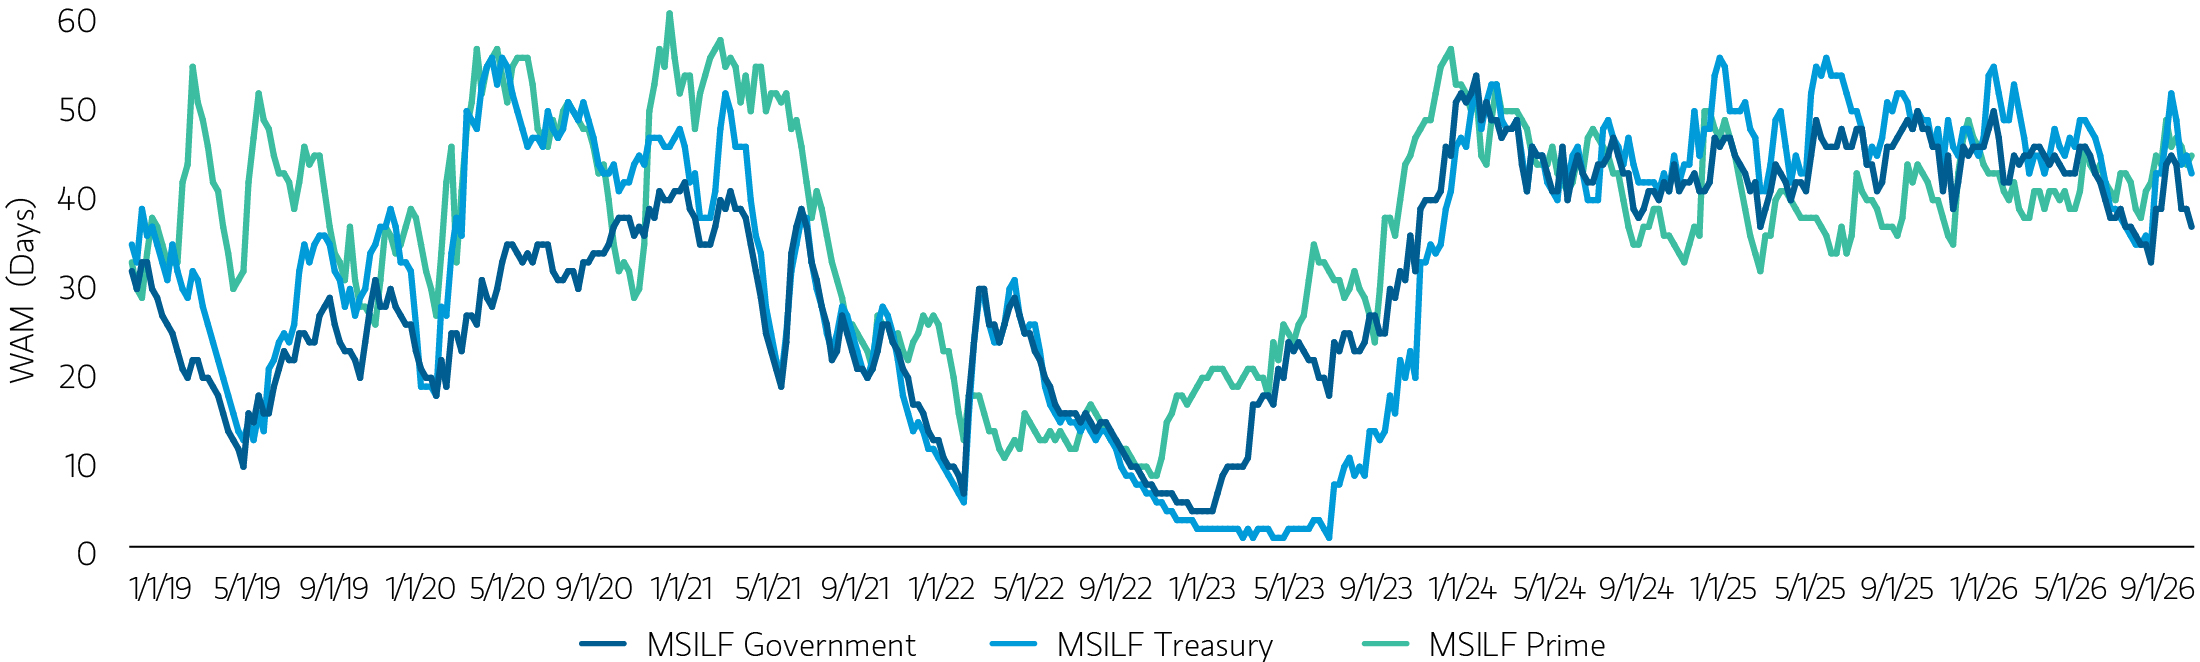
Source: iMoneyNet
MSILF Weighted Average Maturities (WAM) Summary
As of 10/31/26
PORTFOLIO STRATEGY
Government/Treasury Strategy
Market pricing for the next rate hike shifted significantly throughout the month of October as various Fed speakers suggested that the Fed could remain patient regarding the timing of its next move. Given this uncertainty, we continued to allow the portfolios to organically roll down the yield curve. We selectively added some fixed-rate exposures while continuing to favor floating-rate exposures across agency, Treasury and repo products.
The FOMC remained on hold at its October 28th meeting, noting that additional data was needed to determine the appropriate next steps for monetary policy. Cleveland Fed President Hammack and Fed Governor Cook dissented in favor of a 25 basis point increase. At the press conference, Chair Warsh did not provide forward guidance on monetary policy but noted that broader financial conditions had already started to respond to the 25 basis point hike from the September FOMC meeting. We believe the December FOMC is likely to be a “live” meeting.
Treasury bill supply increased in October and is expected to continue rising throughout November. Larger auction sizes have resulted in greater allocations to dealer balance sheets as money market funds remain cautious about adding too much fixed-rate exposure amid an uncertain Fed path. Funding markets experienced increased pressure around October month-end due to higher bill issuance, coupon settlements and Canadian year-end balance sheet constraints. Funding market pressures are expected to ease in early November.
Currently, we have no liquidity concerns to report. However, it is widely anticipated that the New York Fed will resume reserve management purchases (RMPs) in either November or December.
Prime Strategy
October was characterized by two-way volatility in front-end rates. The 2-year Treasury yield moved higher early in the month before retracing to approximately 4.61% at month-end, while the Federal Reserve maintained its target range at 3.75%-4.00%. Against this backdrop, we continued to manage weighted average maturity (WAM) and weighted average life (WAL), by looking to add duration when more than three interest rate hikes were priced in. Extensions remained incremental and focused on high quality, liquid issuers, while seeking to preserve flexibility given ongoing interest rate and funding-market uncertainty.
Credit fundamentals remain stable and resilient, in our view, with no material deterioration across the high quality issuer universe. However, spreads began to widen around Canadian banks’ year-end as seasonal balance sheet and funding dynamics increased dispersion across the market. Value continues to vary meaningfully by issuer, tenor, structure and liquidity. Select wholesale funding instruments remain attractive on a relative value basis, while opportunities in bonds have been more idiosyncratic and require greater selectivity. We continue to favor a balanced mix of wholesale and bond exposure, with a disciplined focus on liquidity and credit quality. Overall, liquidity conditions remain healthy, supported by solid dealer capacity and consistent demand for high quality, short-duration assets.
1 Source: U.S. Bureau of Labor Statistics
2 Source: Eurostat
3 Source: Bank of England
4 Source: U.K. Office for National Statistics
Featured Insights


One basis point = 0.01%
The index performance is provided for illustrative purposes only and is not meant to depict the performance of a specific investment.
The views and opinions and/or analysis expressed are those of the author or the investment team as of the date of preparation of this material and are subject to change at any time without notice due to market or economic conditions and may not necessarily come to pass. Furthermore, the views will not be updated or otherwise revised to reflect information that subsequently becomes available or circumstances existing, or changes occurring, after the date of publication. The views expressed do not reflect the opinions of all investment personnel at Morgan Stanley Investment Management (MSIM) and its subsidiaries and affiliates ("collectively the Firm”) or the views of the firm as a whole, and may not be reflected in all the strategies and products that the Firm offers.
Forecasts and/or estimates provided herein are subject to change and may not actually come to pass. Information regarding expected market returns and market outlooks is based on the research, analysis and opinions of the authors or investment team. These conclusions are speculative in nature, may not come to pass and are not intended to predict the future performance of any specific strategy or product the Firm offers. Future results may differ significantly depending on factors such as changes in securities or financial markets or general economic conditions.
This material has been prepared on the basis of publicly available information, internally developed data and other third-party sources believed to be reliable. However, no assurances are provided regarding the reliability of such information and the Firm has not sought to independently verify information taken from public and third-party sources.
This material is a general communication, which is not impartial and all information provided has been prepared solely for informational and educational purposes and does not constitute an offer or a recommendation to buy or sell any particular security or to adopt any specific investment strategy. The information herein has not been based on a consideration of any individual investor circumstances and is not investment advice, nor should it be construed in any way as tax, accounting, legal or regulatory advice. To that end, investors should seek independent legal and financial advice, including advice as to tax consequences, before making any investment decision.
Charts and graphs provided herein are for illustrative purposes only. Past performance is no guarantee of future results.
The indexes are unmanaged and do not include any expenses, fees or sales charges. It is not possible to invest directly in an index. Any index referred to herein is the intellectual property (including registered trademarks) of the applicable licensor. Any product based on an index is in no way sponsored, endorsed, sold or promoted by the applicable licensor and it shall not have any liability with respect thereto.
This material is not a product of Morgan Stanley’s Research Department and should not be regarded as a research material or a recommendation.
Current and future portfolio holdings are subject to change. The forecasts in this piece are not necessarily those of Morgan Stanley, and may not actually come to pass.
Certain information herein is based on data obtained from third party sources believed to be reliable. However, we have not verified this information, and we make no representations whatsoever as to its accuracy or completeness.
Please consider the investment objectives, risks, charges and expenses of the portfolios carefully before investing. The prospectus contains this and other information about the portfolios. To obtain a prospectus, download one at www.morganstanley.com/liquidity or call 1.800.236.0992. Please read the prospectus carefully before investing.
There is no assurance that a portfolio will achieve its investment objective. Portfolios are subject to market risk, which is the possibility that the market values of securities owned by the portfolio will decline and that the value of portfolio shares may therefore be less than what you paid for them. Market values can change daily due to economic and other events (e.g. natural disasters, health crises, terrorism, conflicts and social unrest) that affect markets, countries, companies or governments. It is difficult to predict the timing, duration, and potential adverse effects (e.g. portfolio liquidity) of events.
STABLE NAV
You could lose money by investing in the Fund. Although the Fund seeks to preserve the value of your investment at $1.00 per share, it cannot guarantee it will do so. An investment in the Fund is not a bank account and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. The Fund’s sponsor is not required to reimburse the Fund for losses, and you should not expect that the sponsor will provide financial support to the Fund at any time, including during periods of market stress.
FLOATING NAV
You could lose money by investing in the Fund. Because the share price of the Fund will fluctuate, when you sell your shares they may be worth more or less than what you originally paid for them. The Fund may impose a fee upon sale of your shares. The Fund generally must impose a fee when net sales of Fund shares exceed certain levels. An investment in the Fund is not a bank account and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. The Fund’s sponsor is not required to reimburse the Fund for losses, and you should not expect that the sponsor will provide financial support to the Fund at any time, including during periods of market stress. The Portfolio will be required to price and transact in their shares at a floating Net asset value (“NAV”). The Portfolio will be required to impose a mandatory liquidity fee when the Fund experiences daily net redemptions that exceed 5% of net assets, unless the Fund’s liquidity costs are de minimis.
Morgan Stanley Investment Management is the asset management division of Morgan Stanley.
NOT FDIC INSURED. OFFER NO BANK GUARANTEE. MAY LOSE VALUE. NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY.


