
 Top

Monthly Review
October reversed many of September’s dominant market moves. Government bonds rallied broadly across developed markets while credit spreads widened following a month in which rates and spreads had moved in the opposite direction. Rate volatility declined modestly even as equity volatility increased, while the Federal Reserve, European Central Bank and Bank of Japan all paused after tightening in September. The result was a clear shift in market pressure from rates toward credit, with the weakness particularly pronounced in Europe.
The government bond rally was broad and driven primarily by real yields. The U.S. 10-year Treasury yield fell 36 basis points (bps) to 4.93% after trading above 5% for much of the month. The belly of the curve led the rally, while the two-year declined somewhat less, leaving the front end flatter and the long end modestly steeper. Ten-year real yields fell 33 bps while breakevens declined only 3 bps, indicating that the move largely reflected a repricing of real rates rather than a meaningful change in the inflation outlook. Bund yields declined 26 bps and Japanese government bonds rallied further, while gilts lagged. Euro-area sovereign spreads moved in the opposite direction. France widened 38 bps versus Germany to 165 bps, its widest level since the 2012 sovereign debt crisis, amid budget negotiations and political uncertainty ahead of the 2027 presidential election, while Italy also widened in sympathy.
The major central banks largely paused in unison. The Federal Reserve held its target range at 3.75%-4.00% on October 28 by a vote of 10 to two, with both dissenters favoring a further increase, while upgrading its characterization of economic growth from solid to strong. The ECB held its deposit facility rate at 2.50% the following day after discussing a potential hike, while Christine Lagarde announced plans to step down in February 2027. The Bank of Japan also held its policy rate at 1.25% by an eight-to-one vote. The Bank of Canada was the exception, raising its policy rate 25 bps to 2.50%, its first increase since 2023. The pauses did not represent a dovish shift. Euro-area inflation reached 3.8% in September and U.S. inflation 3.7%, while futures markets ended October pricing a December hike as the more likely outcome on both sides of the Atlantic.
Currency markets were comparatively subdued. The broad U.S. dollar index rose 0.3%, while the euro declined 1.5%. The Norwegian krone led major currencies, appreciating 4.5% alongside a further 13.6% rise in oil to approximately $118 per barrel, while the Canadian dollar also strengthened following the Bank of Canada’s rate increase. Latin American currencies were weaker, with the Brazilian real declining 4.9% and the Mexican peso also falling. The limited move in the dollar despite the substantial decline in U.S. yields reflected the broad nature of the global bond rally rather than a uniquely U.S. rates adjustment.
Investment-grade credit weakened further. U.S. spreads widened 10 bps to 90 bps option-adjusted spread (OAS), with industrials underperforming financials, while Euro investment grade widened 14 bps to 105 bps and sterling credit moved wider by a similar amount. European financials underperformed industrials. The widening appeared to reflect technical and macro pressures more than a deterioration in underlying corporate fundamentals. Heavy issuance from U.S. technology companies funding artificial intelligence infrastructure increased competition for investor capital, while French sovereign volatility provided an additional headwind to European credit.
High yield experienced substantially greater pressure, particularly in Europe. U.S. high yield widened 29 bps to 340 bps, with BB-rated debt relatively resilient, while CCC spreads widened 108 bps. Euro high yield widened 65 bps to 370 bps, more than twice the U.S. move, while CCC-rated spreads widened an extraordinary 453 bps. Sterling high yield weakened further. The pattern extended the quality differentiation seen over the prior two months. In August, lower-quality credit cheapened even as the broader index tightened, while September and October saw CCC spreads widen at several times the pace of the overall market. The persistence of this dispersion increasingly reflects a distinction between stronger issuers that retain ready access to capital and weaker credits facing a substantially higher financing hurdle.
Securitized markets reversed September’s pattern. Agency mortgage-backed security (MBS) spreads finished broadly unchanged as the MOVE index of implied rate volatility declined 9%, alleviating the principal source of pressure from the prior month. Securitized credit weakened instead, with AAA asset-backed securities (ABS) widening 11 bps and BBB commercial mortgage-backed securities (CMBS) widening by a similar amount, representing the first meaningful widening in consumer and commercial securitized credit in several months. The divergent performance of Agency MBS and securitized credit over the past two months reinforces that the sectors are responding to different underlying drivers rather than a common market shock.
Emerging-market external sovereign and corporate spread data were unavailable in this month’s dataset, so those markets are not included in the review. Local markets were sharply differentiated. Brazilian 10-year yields rose 116 bps and Indonesian yields also moved materially higher, while Korean yields declined 41 bps and yields in Mexico and Hungary fell more modestly. Brazil stood out, with the increase in yields occurring alongside a 4.9% decline in the real despite a central bank that has been easing policy throughout the year, pointing toward domestic fiscal and political concerns rather than the broader global rates rally.
Overall, October was characterized by a shift from rates-driven volatility toward credit differentiation. Duration was broadly rewarded while spread risk came under pressure, with the weakness concentrated in Europe and lower-quality credit. French sovereign concerns, elevated energy prices and growing competition for capital from AI-related issuance all contributed to a more challenging technical backdrop. With major central banks paused but further tightening still priced, and dispersion continuing to widen across ratings and regions, carry, relative value and active security selection remained increasingly important drivers of return.
Display 1: Asset Performance Year-to-Date (%)
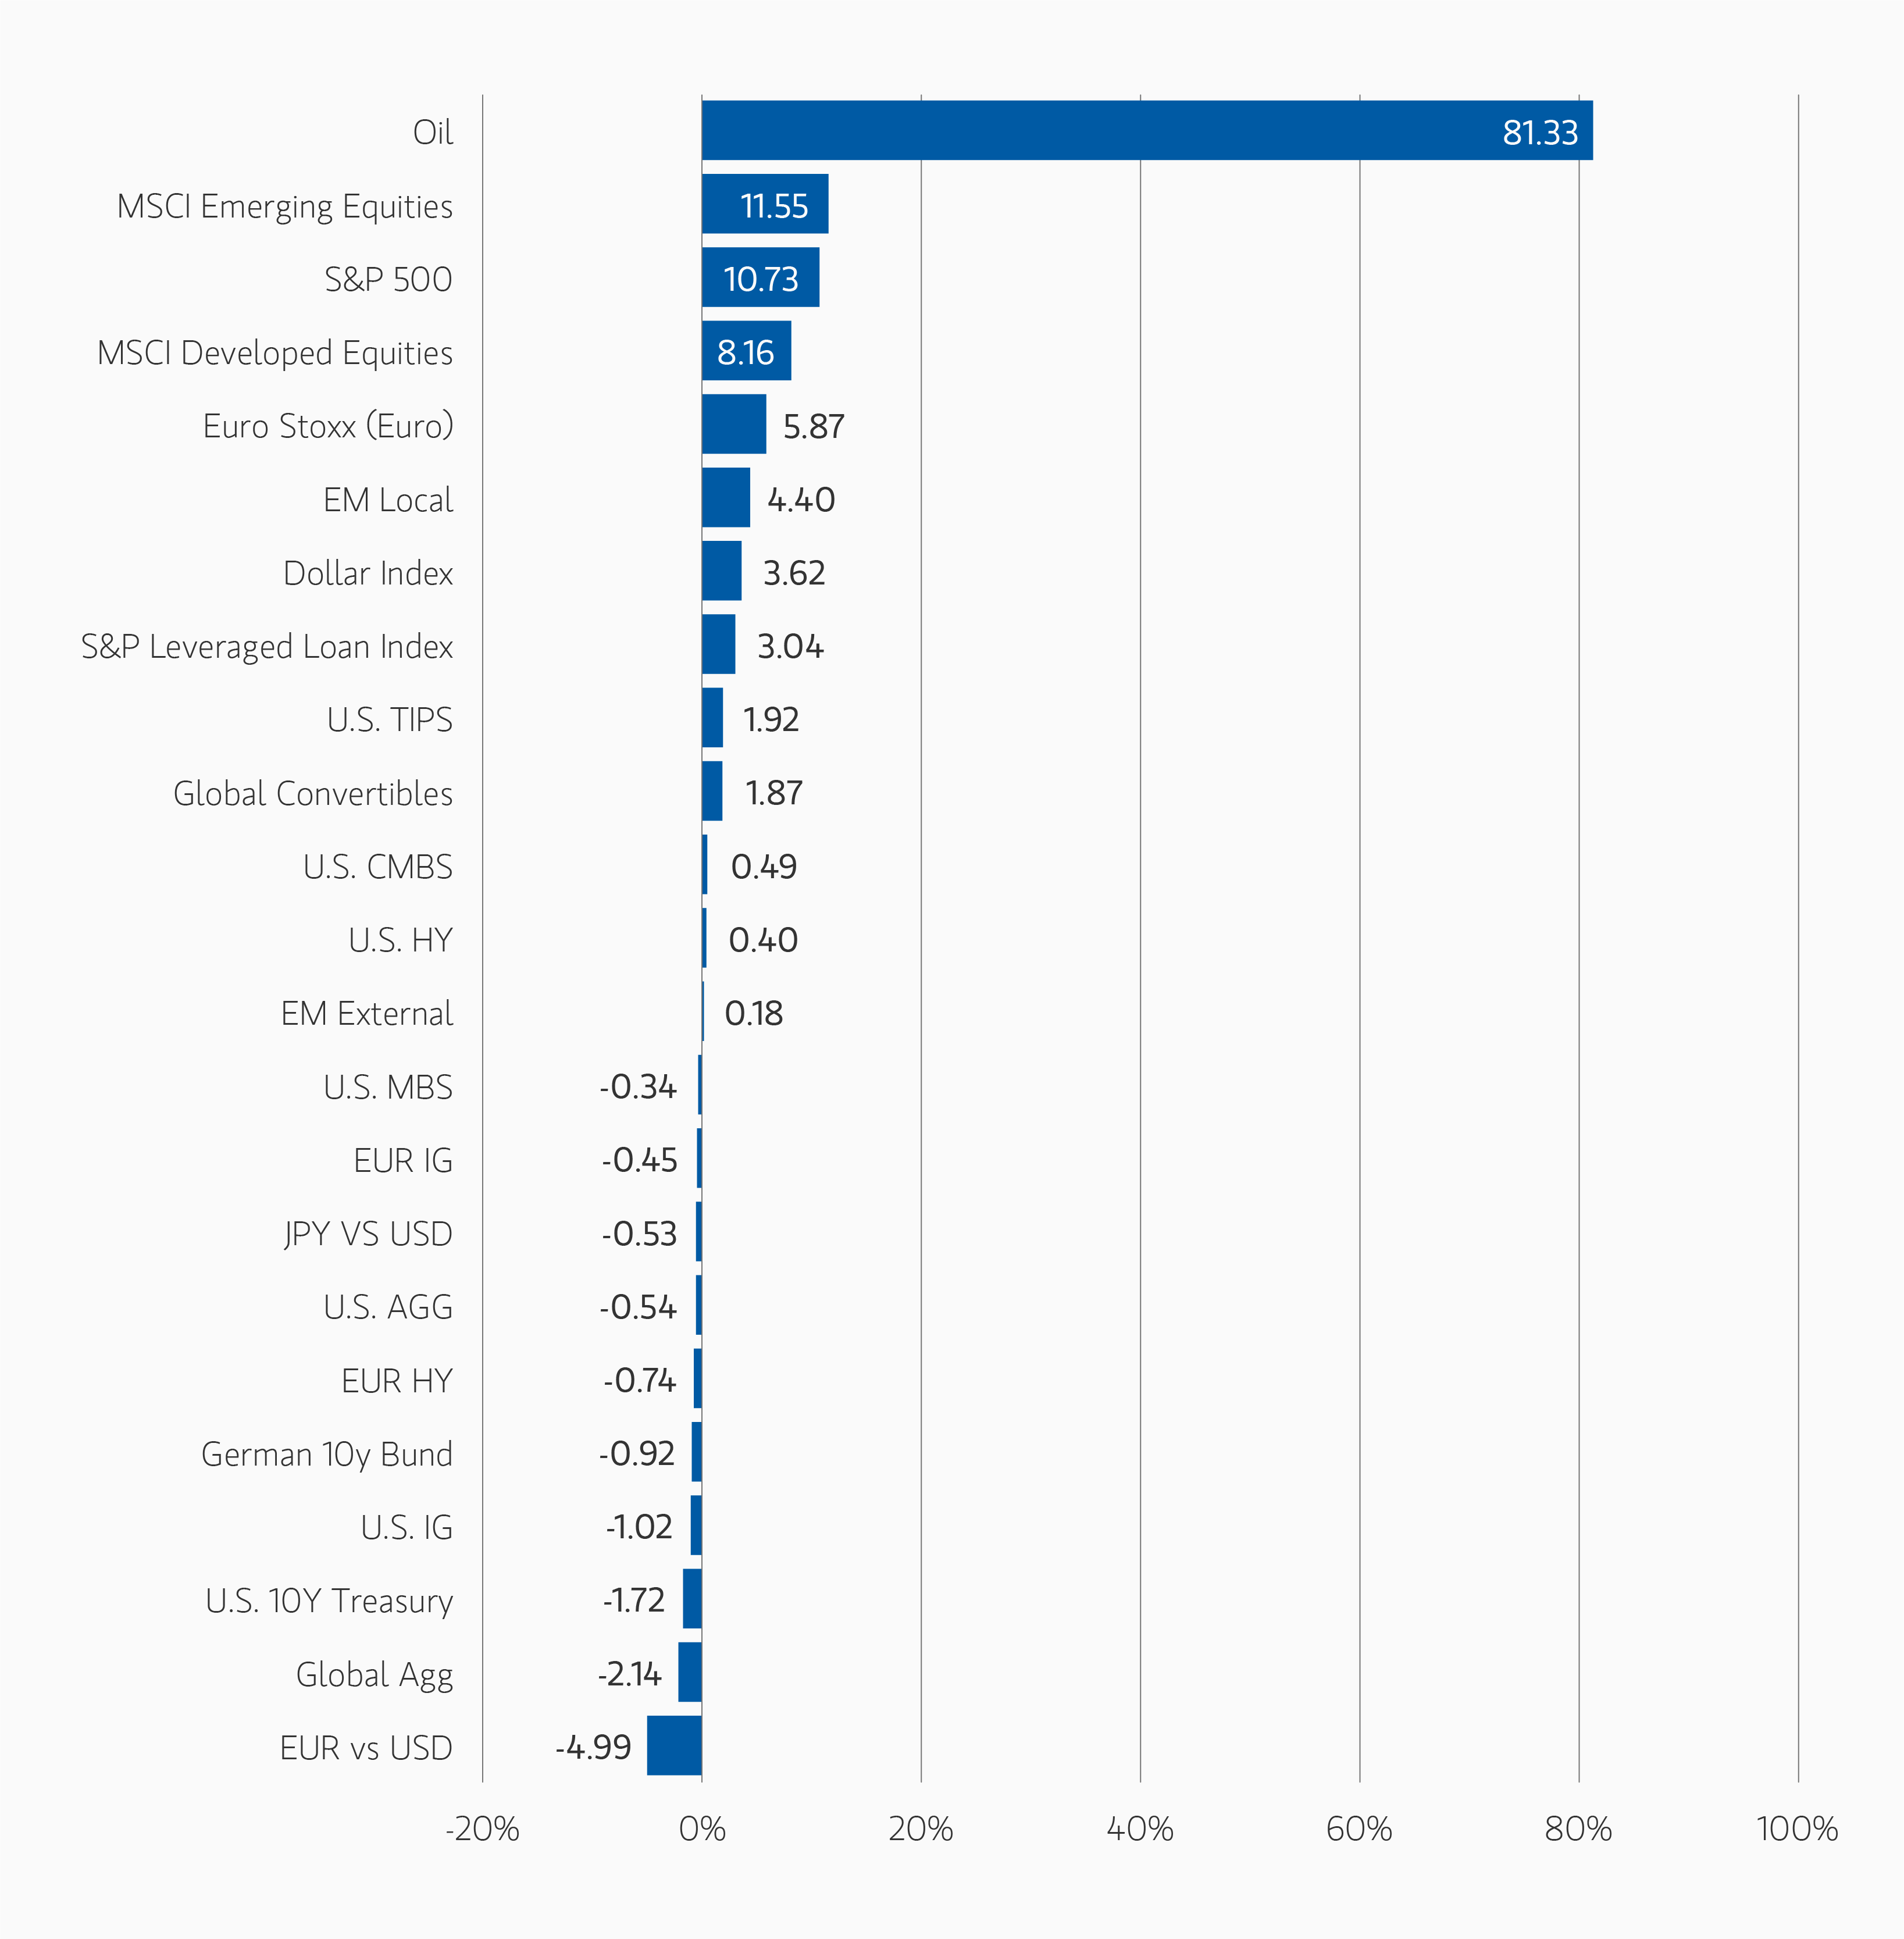
Note: USD-based performance. Source: Bloomberg. Data as of October 31, 2026. The indexes are provided for illustrative purposes only and are not meant to depict the performance of a specific investment. Past performance is no guarantee of future results. See pages 12-15 for index definitions. Past performance is no guarantee of future results.
Display 1: Asset Performance Year-to-Date (%)
Display 2: Currency Monthly Changes versus USD
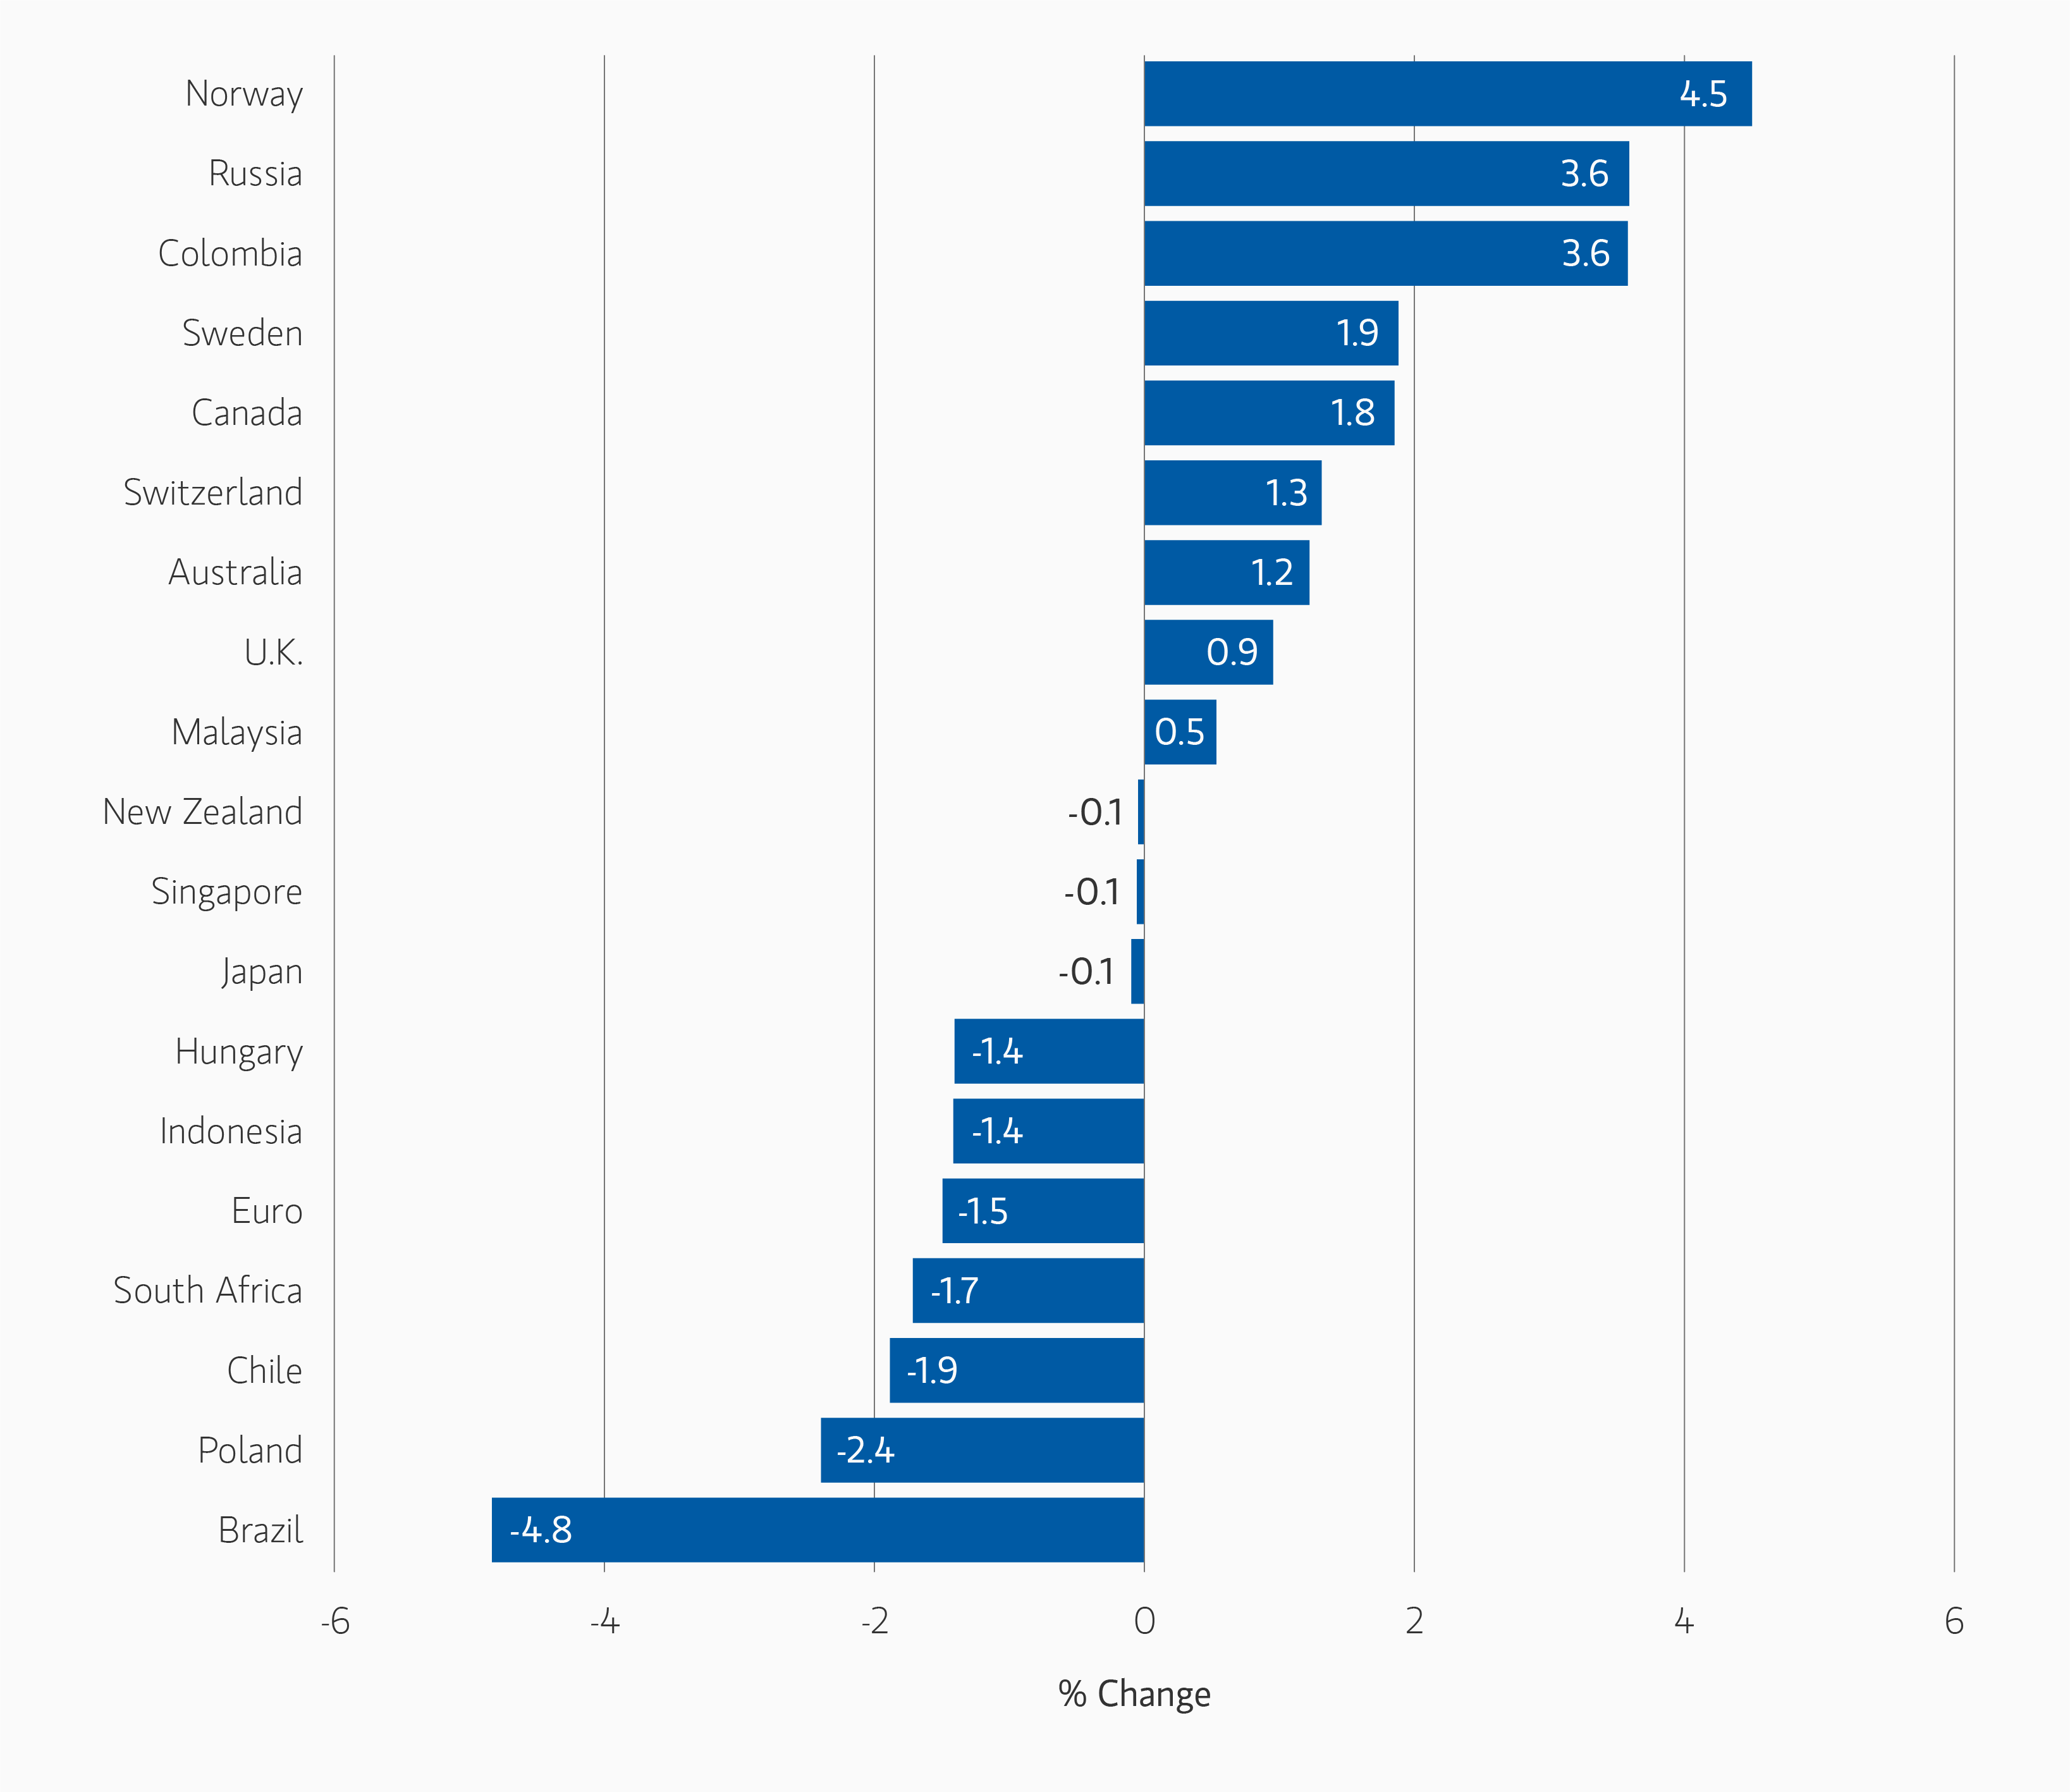
Note: Positive change means appreciation of the currency against the USD. Source: Bloomberg. Data as of October 31, 2026.
Display 2: Currency Monthly Changes versus USD
Display 3: Major Monthly Changes in 10-Year Yields and Spreads
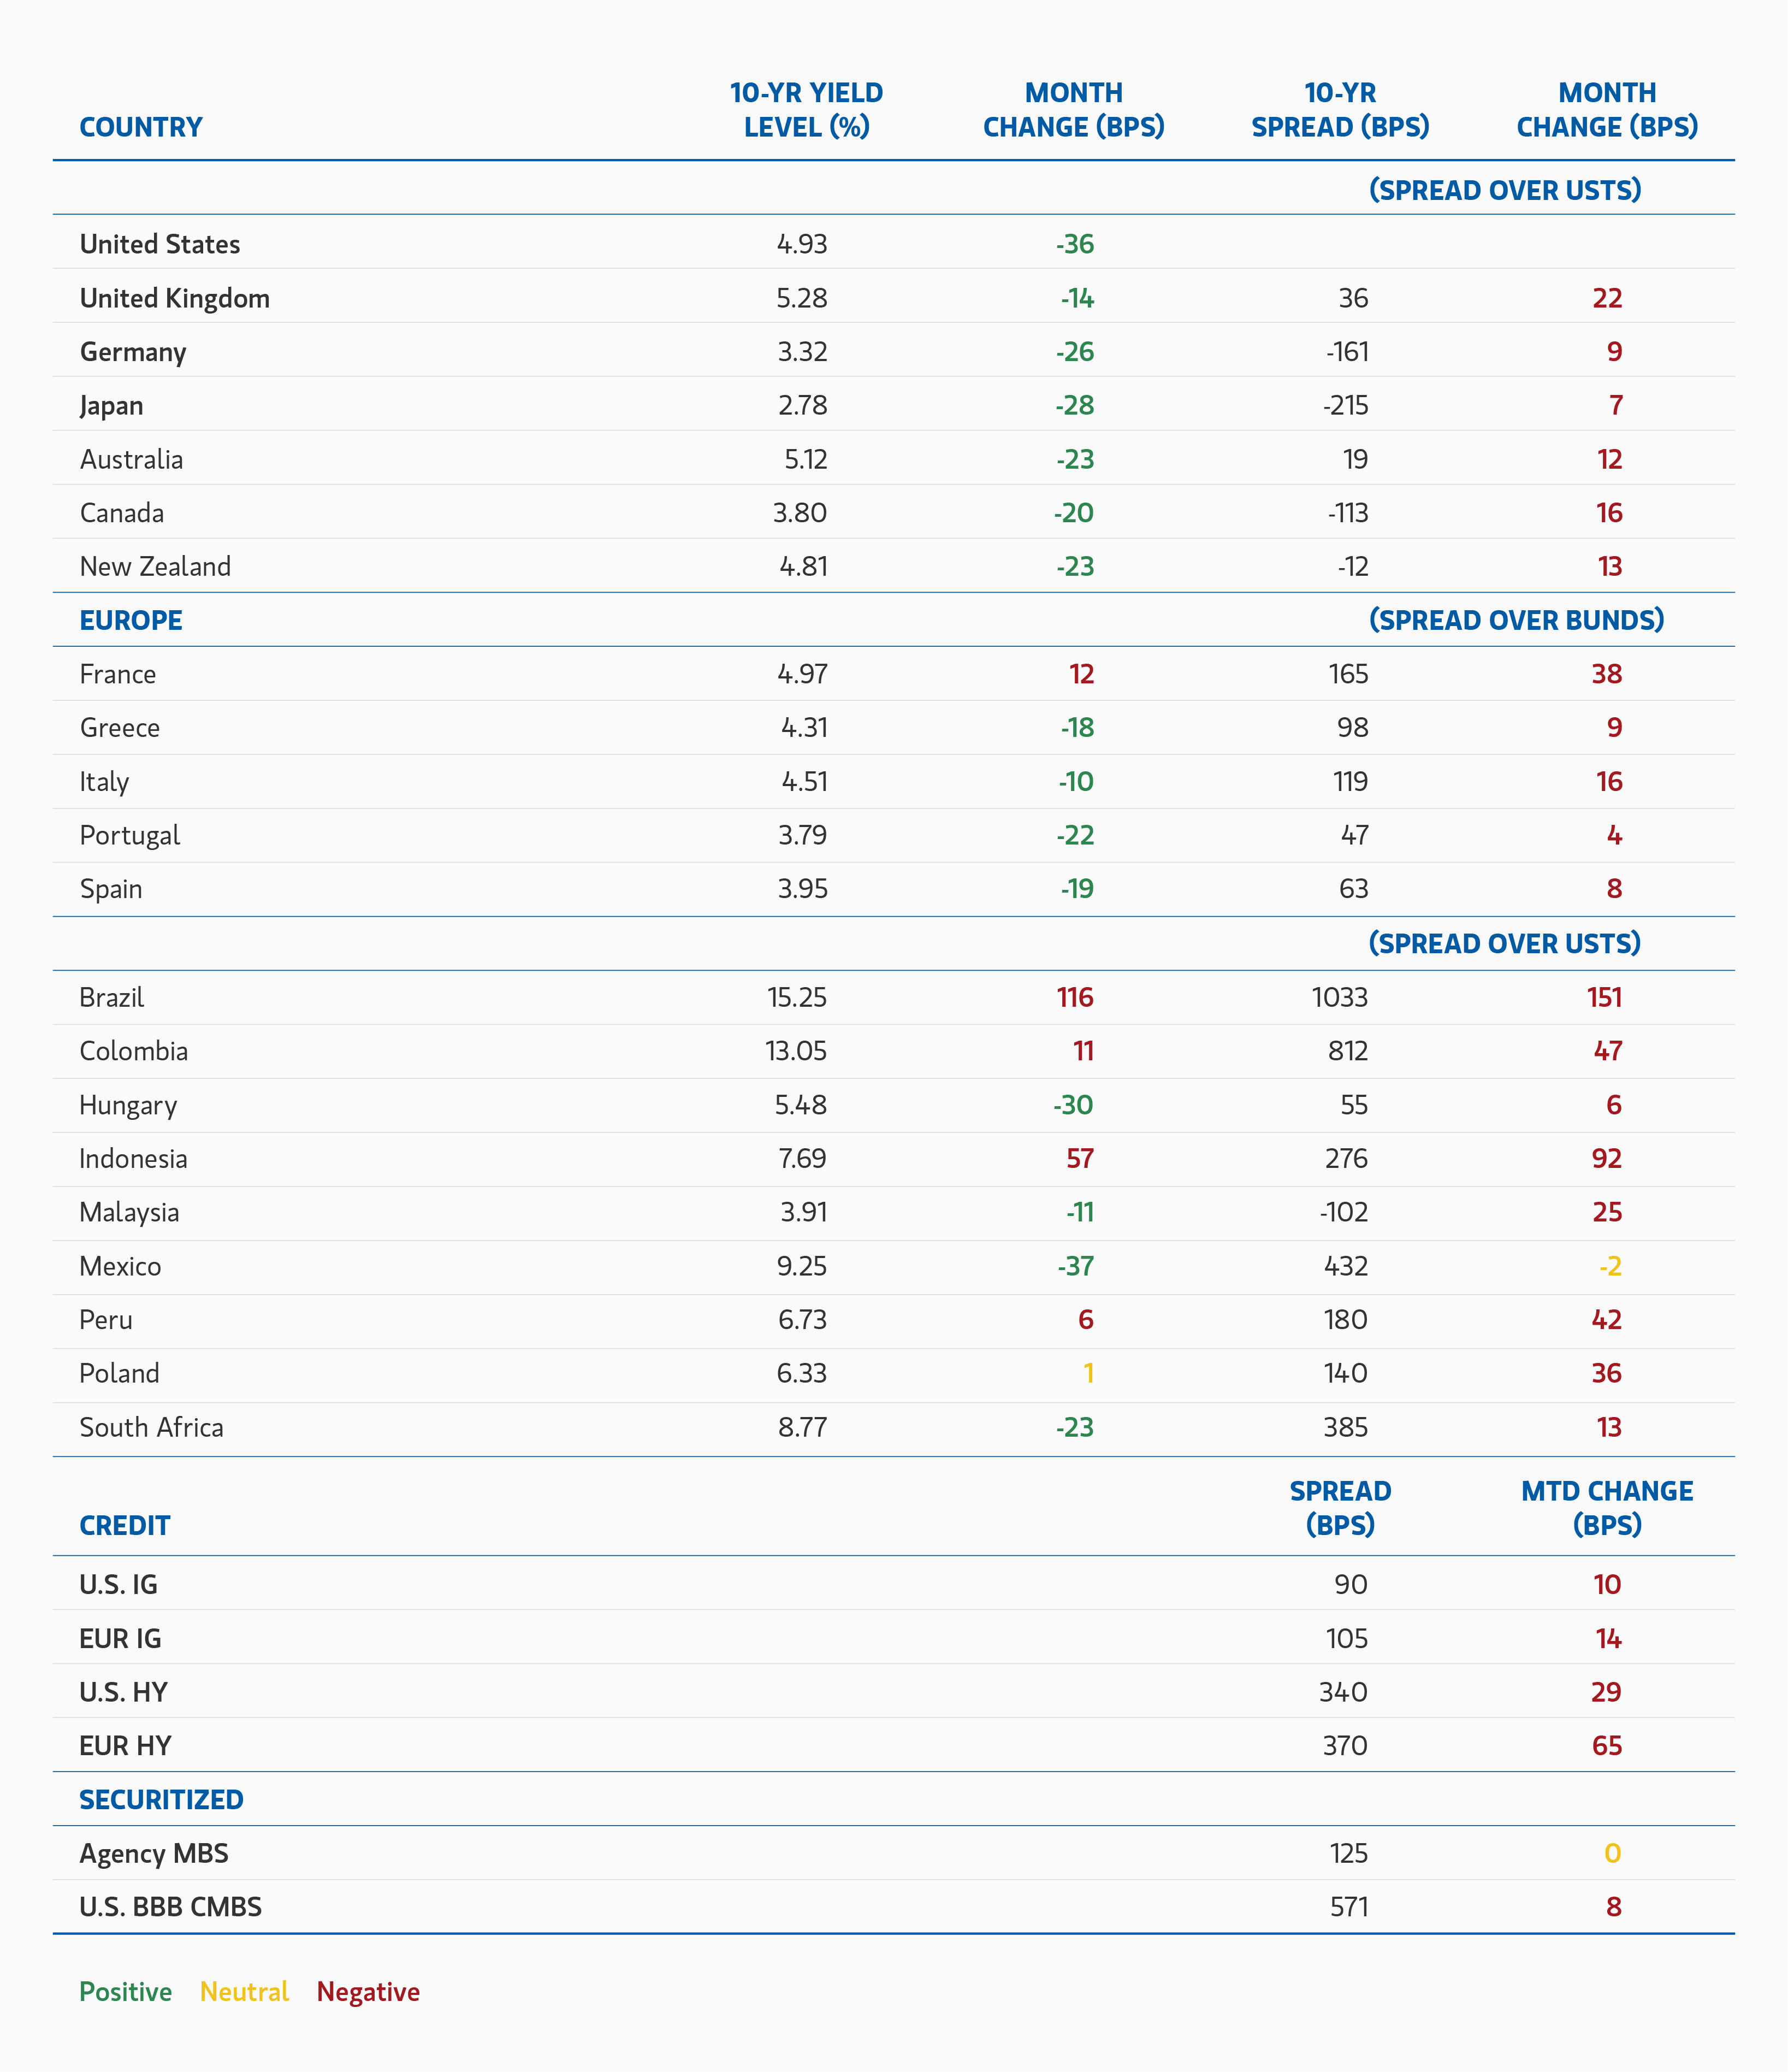
Source: Bloomberg, JPMorgan. Data as of October 31, 2026.
Display 3: Major Monthly Changes in 10-Year Yields and Spreads
Broad Markets Fixed Income Global Asset Allocation and Outlook
Developed Market Rate/Foreign Currency
(Selective duration, relative-value curve positioning, neutral foreign exchange (FX))
Our outlook remains grounded in an environment where economic growth has proven resilient, but restrictive monetary policy is likely to exert greater influence over activity as we move forward. Inflation remains above central-bank targets across several developed markets, keeping policymakers cautious even as the cumulative effects of higher rates begin to emerge. We therefore expect monetary-policy paths to remain differentiated across countries, creating opportunities through relative value rather than broad directional positioning.
Against this backdrop, we have reduced our overall conviction in developed-market duration and favor a more selective approach. We continue to see opportunities in markets where monetary policy appears restrictive relative to domestic growth prospects, particularly outside the United States, but believe elevated inflation and the possibility of further tightening argue against maintaining a substantial broad duration bias. At the same time, current yield levels provide a meaningful income cushion and should increasingly constrain interest-rate-sensitive areas of the economy.
Inflation remains an important macro risk, and we continue to see value in U.S. inflation-linked markets. Persistent underlying price pressures, elevated nominal growth and uncertainty around the timing and extent of further Federal Reserve tightening support maintaining mitigation against the risk that inflation remains above target for longer than markets anticipate.
Curve opportunities are increasingly driven by differences in monetary policy, fiscal dynamics and term premia across developed markets rather than by a single global steepening or flattening view. We therefore favor selective cross-market relative-value opportunities while maintaining limited conviction in broad directional curve positioning.
In foreign exchange, we currently maintain a neutral stance. Recent currency moves have been heavily influenced by shifting central-bank expectations, relative real yields and changes in global risk sentiment, leaving fewer compelling directional opportunities. We remain prepared to add exposure where valuation, carry and policy divergence create more attractive asymmetric opportunities.
Emerging Market Debt
(Reducing overweight)
We continue to reduce our overweight to emerging-market debt following a period of strong performance, tight credit valuations and a less supportive global policy backdrop. Elevated real yields and improving fundamentals continue to create attractive opportunities in select countries, but broad EM credit spreads offer less compensation than earlier in the year, and we remain cautious about adding broad market risk.
Recent developments have reinforced the importance of country differentiation. Lower oil prices should provide support to energy-importing economies, particularly in parts of Asia, while several central banks in the region remain relatively hawkish despite lower global yields. This creates selective opportunities in local rates where inflation risks ease and policy can eventually become less restrictive.
Brazil remains a key area of caution following renewed political and fiscal uncertainty, which has weighed on both the currency and domestic assets, and may limit the central bank's ability to ease as aggressively as previously anticipated. Elsewhere, country-specific policy and political developments continue to dominate performance, reinforcing our preference for targeted local-rate and relative-value opportunities rather than broad EM credit or FX exposure.
Carry and income remain important sources of expected return, but current valuations require greater selectivity. We continue to favor countries with credible monetary frameworks, improving external balances and attractive real-yield differentials while maintaining a relatively light overall risk posture and preserving flexibility to add exposure should valuations become more compelling.
Corporate Credit
(Underweight investment grade (IG), small overweight high yield (HY))
We remain underweight investment-grade corporates while maintaining a small overweight to select high-yield issuers. Recent widening and higher all-in yields have improved prospective returns across corporate credit, but the opportunity set remains highly differentiated by region, sector, issuer and capital structure. We therefore continue to favor carry and security selection over broad credit beta.
The macro backdrop remains broadly supportive, although growth is becoming increasingly differentiated across regions. U.S. activity remains comparatively resilient, supported by healthy labor markets and continued investment in AI, data centers, energy infrastructure and broader capital expenditure. European growth is likely to remain more moderate, with increased fiscal spending providing some support but sovereign risks, particularly in France, creating a more challenging technical backdrop for credit.
Corporate fundamentals also remain broadly healthy following a strong reporting season, supported by solid earnings and generally robust balance sheets. However, later-cycle behaviors are becoming more visible through increased M&A activity, elevated capital expenditure, higher shareholder distributions and rising financing requirements. These trends are likely to increase dispersion and place greater emphasis on sector allocation, capital-structure positioning and bottom-up security selection.
Within investment grade, attractive all-in yields continue to support institutional demand despite substantial issuance. However, supply remains an important consideration as M&A financing, AI-related investment, hyperscaler issuance and infrastructure spending are likely to keep primary markets active, particularly among non-financial issuers. We no longer maintain a broad preference for Europe over the U.S. and instead favor a more balanced regional approach centered on relative value and issuer selection. European credit continues to face greater pressure from sovereign volatility, energy prices and heavier technical supply, while U.S. credit has generally benefited from stronger demand and more favorable all-in yields.
The recent widening has also created selective opportunities in areas of IG that previously offered insufficient compensation. This is particularly true in technology and data center-related issuance, although the threshold for participation remains high. We continue to require sufficient spread compensation for construction, financing, execution, tenant and other idiosyncratic risks rather than treating AI-related issuance as a broad thematic opportunity.
High yield has also become more attractive following recent spread widening and higher yields. Flows have improved, primary markets remain functional and new issues are generally coming with better concessions and more disciplined structures. We continue to favor BB and higher-quality single-B issuers over CCC and distressed credits, where dispersion remains elevated and earnings misses are being punished more severely. We prefer businesses with resilient cash flows, strong liquidity, manageable refinancing needs and less exposure to highly cyclical demand.
AI and data center financing has become an increasingly important part of both the investment-grade and high-yield opportunity sets. While these securities can offer attractive spread premiums, we remain highly selective and focus on projects with strong tenants, credible lease structures, reliable access to power and infrastructure, and clear paths to completion. We remain more cautious where construction risk, financing requirements or the durability of the eventual end user are less certain.
Overall, recent widening has improved the opportunity set across corporate credit, but spreads remain relatively tight in many higher-quality sectors and dispersion continues to rise. We therefore expect carry, new-issue concessions, relative value and security selection to remain the primary sources of excess return rather than broad spread compression.
Leveraged Loans
(Neutral)
We maintain a neutral stance on leveraged loans. The asset class continues to benefit from strong collateralized loan obligation (CLO) demand and demand for floating-rate exposure, helping loans hold up comparatively well through recent market volatility. Higher-quality BB and single-B issuers have generally remained resilient, while widening has been concentrated more heavily in lower-quality credits.
Dispersion remains elevated across sectors and issuers. We continue to exercise caution in CCC credits, software, health care and selected cyclical industrials, where refinancing risk, weaker earnings or structural disruption may create greater downside. Software remains particularly differentiated as AI-related disruption continues to challenge some business models, while approaching maturities may create a more difficult refinancing environment for weaker issuers.
Data center exposure also requires careful underwriting. We favor operating or well-funded assets with investment-grade tenants, secured access to power, clear completion paths and structures that amortize over time. By contrast, unfinished projects with substantial future funding commitments or uncertain infrastructure access present materially greater risk.
Although elevated policy rates continue to increase borrowing costs, we have not yet seen a broad deterioration in loan fundamentals. Strong CLO technicals remain an important source of support, but current dispersion reinforces our preference for higher-quality issuers and sectors where cash-flow visibility and refinancing capacity remain strong.
Securitized Products
(Overweight)
We remain overweight securitized products, although the opportunity set has become increasingly differentiated across agency and non-agency markets. Recent spread widening across securitized credit has improved prospective returns, while underlying collateral fundamentals remain broadly stable. We continue to favor sectors and structures where wider spreads reflect macro and rates volatility rather than a deterioration in credit quality.
Agency MBS remain attractive from a carry and diversification perspective, supported by elevated mortgage rates, limited refinancing activity, constrained supply and lower rate volatility compared with recent peaks. However, following the tightening seen in October, valuations are closer to fair value on a volatility-adjusted basis. We therefore remain constructive but more selective, with greater emphasis on carry, convexity and structure rather than expecting significant further spread compression.
Non-agency residential mortgage-backed securities (RMBS) has become increasingly attractive following recent widening. Higher-quality non-qualified mortgage (non-QM) securities now offer greater spread compensation than earlier in the year, while underlying housing fundamentals remain broadly stable. We continue to favor higher-quality structures where investors can capture meaningful incremental yield without taking excessive lower-tier credit risk.
Commercial mortgage-backed securities remain attractive selectively. We continue to favor high-quality single-asset single-borrower transactions backed by strong properties and sponsors while avoiding lower-quality collateral where refinancing risk or weaker sponsorship could lead to greater impairment. Data center CMBS has underperformed other property types and remains an area of caution given construction, technology, power, tenant and obsolescence risks. We prefer stabilized, cash-flowing assets over speculative or unfinished projects.
Asset-backed securities continue to offer attractive diversification, particularly in shorter-duration and amortizing structures. Traditional consumer sectors such as cards and autos have remained comparatively resilient, while digital-infrastructure ABS has widened more materially. We remain selective in data center-related ABS and require sufficient compensation for technology, execution and asset-obsolescence risks.
Overall, recent widening has improved the relative-value opportunity across securitized credit, particularly in higher-quality non-agency RMBS, select SASB CMBS and defensive ABS. We continue to favor areas where strong collateral fundamentals, visible cash flows and improved spreads provide attractive carry without requiring excessive credit risk.

RISK CONSIDERATIONS
Diversification neither assures a profit nor guarantees against loss in a declining market.
There is no assurance that a portfolio will achieve its investment objective. Portfolios are subject to market risk, which is the possibility that the market values of securities owned by the portfolio will decline and that the value of portfolio shares may therefore be less than what you paid for them. Market values can change daily due to economic and other events (e.g., natural disasters, health crises, terrorism, conflicts, and social unrest) that affect markets, countries, companies, or governments. It is difficult to predict the timing, duration, and potential adverse effects (e.g., portfolio liquidity) of events. Accordingly, you can lose money investing in a portfolio. Fixed-income securities are subject to the ability of an issuer to make timely principal and interest payments (credit risk), changes in interest rates (interest rate risk), the creditworthiness of the issuer and general market liquidity (market risk). In a rising interest-rate environment, bond prices may fall and may result in periods of volatility and increased portfolio redemptions. In a declining interest-rate environment, the portfolio may generate less income. Longer-term securities may be more sensitive to interest rate changes. Certain U.S. government securities purchased by the strategy, such as those issued by Fannie Mae and Freddie Mac, are not backed by the full faith and credit of the U.S. It is possible that these issuers will not have the funds to meet their payment obligations in the future. Public bank loans are subject to liquidity risk and the credit risks of lower-rated securities. High-yield securities (junk bonds) are lower-rated securities that may have a higher degree of credit and liquidity risk. Sovereign debt securities are subject to default risk. Mortgage- and asset-backed securities are sensitive to early prepayment risk and a higher risk of default and may be hard to value and difficult to sell (liquidity risk). They are also subject to credit, market, and interest rate risks. The currency market is highly volatile. Prices in these markets are influenced by, among other things, changing supply and demand for a particular currency; trade; fiscal, money and domestic or foreign exchange control programs and policies; and changes in domestic and foreign interest rates. Investments in foreign markets entail special risks such as currency, political, economic and market risks. The risks of investing in emerging market countries are greater than the risks generally associated with foreign investments. Derivative instruments may disproportionately increase losses and have a significant impact on performance. They also may be subject to counterparty, liquidity, valuation, and correlation and market risks. Restricted and illiquid securities may be more difficult to sell and value than publicly traded securities (liquidity risk). Due to the possibility that prepayments will alter the cash flows on collateralized mortgage obligations (CMOs), it is not possible to determine in advance their final maturity date or average life. In addition, if the collateral securing the CMOs or any third-party guarantees are insufficient to make payments, the portfolio could sustain a loss.
DEFINITIONS
Basis point (bp): One basis point = 0.01%.
INDEX DEFINITIONS
The indexes shown in this report are not meant to depict the performance of any specific investment, and the indexes shown do not include any expenses, fees, or sales charges, which would lower performance. The indexes shown are unmanaged and should not be considered an investment. It is not possible to invest directly in an index.
“Bloomberg®” and the Bloomberg Index/Indices used are service marks of Bloomberg Finance L.P. and its affiliates and have been licensed for use for certain purposes by Morgan Stanley Investment Management (MSIM). Bloomberg is not affiliated with MSIM, does not approve, endorse, review, or recommend any product, and does not guarantee the timeliness, accurateness, or completeness of any data or information relating to any product.
The Bloomberg Euro Aggregate Corporate Index (Bloomberg Euro IG Corporate) is an index designed to reflect the performance of the euro-denominated investment-grade corporate bond market.
The Bloomberg Global Aggregate Corporate Index is the corporate component of the Bloomberg Global Aggregate index, which provides a broad-based measure of the global investment-grade fixed income markets.
The Bloomberg US Corporate High Yield Index measures the market of USD-denominated, non-investment grade, fixed-rate, taxable corporate bonds. Securities are classified as high yield if the middle rating of Moody’s, Fitch, and S&P is Ba1/BB+/BB+ or below. The index excludes emerging market debt.
The Bloomberg US Corporate Index is a broad-based benchmark that measures the investment grade, fixed-rate, taxable, corporate bond market.
The Bloomberg US Mortgage-Backed Securities (MBS) Index tracks agency mortgage-backed pass-through securities (both fixed-rate and hybrid ARM) guaranteed by Ginnie Mae (GNMA), Fannie Mae (FNMA) and Freddie Mac (FHLMC). The index is constructed by grouping individual TBA-deliverable MBS pools into aggregates or generics based on program, coupon, and vintage. Introduced in 1985, the GNMA, FHLMC and FNMA fixed-rate indexes for 30- and 15-year securities were backdated to January 1976, May 1977, and November 1982, respectively. In April 2007, agency hybrid adjustable-rate mortgage (ARM) pass-through securities were added to the index.
ICE BofA MOVE Index: The MOVE Index measures U.S. bond market volatility by tracking a basket of OTC options on U.S. interest rate swaps. The Index tracks implied normal yield volatility of a yield curve weighted basket of at-the-money one-month options on the 2-year, 5-year, 10-year, and 30-year constant maturity interest rate swaps.
Consumer Price Index (CPI) is a measure that examines the weighted average of prices of a basket of consumer goods and services, such as transportation, food, and medical care.
Euro vs. USD—Euro total return versus U.S. dollar.
German 10YR bonds—Germany Benchmark 10-Year Datastream Government Index; Japan 10YR government bonds —Japan Benchmark 10-Year Datastream Government Index; and 10YR US Treasury—US Benchmark 10-Year Datastream Government Index.
The ICE BofAML European Currency High-Yield Constrained Index (ICE BofAML Euro HY constrained) is designed to track the performance of euro- and British pound sterling-denominated below investment-grade corporate debt publicly issued in the Eurobond, sterling.
The ICE BofAML US Mortgage-Backed Securities (ICE BofAML US Mortgage Master) Index tracks the performance of US dollar-denominated, fixed-rate and hybrid residential mortgage pass-through securities publicly issued by US agencies in the US domestic market.
The ICE BofAML US High Yield Master II Constrained Index (ICE BofAML US High Yield) is a market value-weighted index of all domestic and Yankee high-yield bonds, including deferred-interest bonds and payment-in-kind securities. Its securities have maturities of one year or more and a credit rating lower than BBB-/Baa3 but are not in default.
The ISM Manufacturing Index is based on surveys of more than 300 manufacturing firms by the Institute of Supply Management. The ISM Manufacturing Index monitors employment, production inventories, new orders, and supplier deliveries. A composite diffusion index is created that monitors conditions in national manufacturing based on the data from these surveys.
Italy 10-Year Government Bonds—Italy Benchmark 10-Year Datastream Government Index.
The JP Morgan CEMBI Broad Diversified Index is a global, liquid corporate emerging markets benchmark that tracks US-denominated corporate bonds issued by emerging markets entities.
The JPMorgan Government Bond Index—emerging markets (JPM local EM debt) tracks local currency bonds issued by emerging market governments. The index is positioned as the investable benchmark that includes only those countries that are accessible by most of the international investor base (excludes China and India as of September 2013).
The JPMorgan Government Bond Index Emerging Markets (JPM External EM Debt) tracks local currency bonds issued by emerging market governments. The index is positioned as the investable benchmark that includes only those countries that are accessible by most of the international investor base (excludes China and India as of September 2013).
The JP Morgan Emerging Markets Bond Index Global (EMBI Global) tracks total returns for traded external debt instruments in the emerging markets and is an expanded version of the EMBI+. As with the EMBI+, the EMBI Global includes US dollar-denominated Brady bonds, loans, and Eurobonds with an outstanding face value of at least $500 million.
The JP Morgan GBI-EM Global Diversified Index is a market-capitalization weighted, liquid global benchmark for US-dollar corporate emerging market bonds representing Asia, Latin America, Europe, and the Middle East/Africa.
JPY vs. USD—Japanese yen total return versus US dollar.
The Markit ITraxx Europe Index comprises 125 equally weighted credit default swaps on investment grade European corporate entities, distributed among 4 sub-indices: Financials (Senior & Subordinated), Non-Financials and HiVol.
The Nikkei 225 Index (Japan Nikkei 225) is a price-weighted index of Japan’s top 225 blue-chip companies on the Tokyo Stock Exchange.
The MSCI AC Asia ex-Japan Index (MSCI Asia ex-Japan) captures large- and mid-cap representation across two of three developed markets countries (excluding Japan) and eight emerging markets countries in Asia.
The MSCI All Country World Index (ACWI, MSCI global equities) is a free float-adjusted market capitalization weighted index designed to measure the equity market performance of developed and emerging markets. The term "free float" represents the portion of shares outstanding that are deemed to be available for purchase in the public equity markets by investors. The performance of the Index is listed in US dollars and assumes reinvestment of net dividends.
MSCI Emerging Markets Index (MSCI emerging equities) captures large- and mid-cap representation across 23 emerging markets (EM) countries.
The MSCI World Index (MSCI developed equities) captures large and mid-cap representation across 23 developed market (DM) countries.
Purchasing Managers Index (PMI) is an indicator of the economic health of the manufacturing sector.
The Refinitiv Convertible Global Focus USD Hedged Index is a market weighted index with a minimum size for inclusion of $500 million (US), 200 million (Europe), 22 billion Yen, and $275 million (Other) of Convertible Bonds with an Equity Link.
The Russell 2000® Index is an index that measures the performance of the 2,000 smallest companies in the Russell 3000 Index.
The S&P 500® Index (US S&P 500) measures the performance of the large-cap segment of the US equities market, covering approximately 75 percent of the US equities market. The index includes 500 leading companies in leading industries of the U.S. economy.
S&P CoreLogic Case-Shiller US National Home Price NSA Index seeks to measure the value of residential real estate in 20 major US metropolitan areas: Atlanta, Boston, Charlotte, Chicago, Cleveland, Dallas, Denver, Detroit, Las Vegas, Los Angeles, Miami, Minneapolis, New York, Phoenix, Portland, San Diego, San Francisco, Seattle, Tampa and Washington, D.C.
The S&P/LSTA US Leveraged Loan 100 Index (S&P/LSTA Leveraged Loan Index) is designed to reflect the performance of the largest facilities in the leveraged loan market.
The S&P GSCI Copper Index (Copper), a sub-index of the S&P GSCI, provides investors with a reliable and publicly available benchmark for investment performance in the copper commodity market.
The S&P GSCI Softs (GSCI soft commodities) Index is a sub-index of the S&P GSCI that measures the performance of only the soft commodities, weighted on a world production basis. In 2012, the S&P GSCI Softs Index included the following commodities: coffee, sugar, cocoa, and cotton.
Spain 10-Year Government Bonds—Spain Benchmark 10-Year Datastream Government Index.
The Thomson Reuters Convertible Global Focus USD Hedged Index is a market weighted index with a minimum size for inclusion of $500 million (US), 200 million euro (Europe), 22 billion yen, and $275 million (Other) of convertible bonds with an equity link.
U.K. 10YR government bonds—U.K. Benchmark 10-Year Datastream Government Index. For the following Datastream government bond indexes, benchmark indexes are based on single bonds. The bond chosen for each series is the most representative bond available for the given maturity band at each point in time. Benchmarks are selected according to the accepted conventions within each market. Generally, the benchmark bond is the latest issue within the given maturity band; consideration is also given to yield, liquidity, issue size and coupon.
The US Dollar Index (DXY) is an index of the value of the United States dollar relative to a basket of foreign currencies, often referred to as a basket of US trade partners’ currencies.
The Chicago Board Options Exchange (CBOE) Market Volatility (VIX) Index shows the market’s expectation of 30-day volatility.
There is no guarantee that any investment strategy will work under all market conditions, and each investor should evaluate their ability to invest for the long-term, especially during periods of downturn in the market.
A separately managed account may not be appropriate for all investors. Separate accounts managed according to the particular strategy may include securities that may not necessarily track the performance of a particular index. Please consider the investment objectives, risks and fees of the Strategy carefully before investing. A minimum asset level is required. For important information about the investment managers, please refer to Form ADV Part 2.
The views and opinions and/or analysis expressed are those of the author or the investment team as of the date of preparation of this material and are subject to change at any time without notice due to market or economic conditions and may not necessarily come to pass. Furthermore, the views will not be updated or otherwise revised to reflect information that subsequently becomes available or circumstances existing, or changes occurring, after the date of publication. The views expressed do not reflect the opinions of all investment personnel at Morgan Stanley Investment Management (MSIM) and its subsidiaries and affiliates (collectively “the Firm”) and may not be reflected in all the strategies and products that the Firm offers.
Forecasts and/or estimates provided herein are subject to change and may not actually come to pass. Information regarding expected market returns and market outlooks is based on the research, analysis and opinions of the authors or the investment team. These conclusions are speculative in nature, may not come to pass and are not intended to predict the future performance of any specific strategy or product the Firm offers. Future results may differ significantly depending on factors such as changes in securities or financial markets or general economic conditions.
This material has been prepared on the basis of publicly available information, internally developed data and other third-party sources believed to be reliable. However, no assurances are provided regarding the reliability of such information and the Firm has not sought to independently verify information taken from public and third-party sources.
This material is a general communication, which is not impartial, and all information provided has been prepared solely for informational and educational purposes and does not constitute an offer or a recommendation to buy or sell any particular security or to adopt any specific investment strategy. The information herein has not been based on a consideration of any individual investor circumstances and is not investment advice, nor should it be construed in any way as tax, accounting, legal or regulatory advice. To that end, investors should seek independent legal and financial advice, including advice as to tax consequences, before making any investment decision.
Charts and graphs provided herein are for illustrative purposes only. Past performance is no guarantee of future results.
The indexes are unmanaged and do not include any expenses, fees, or sales charges. It is not possible to invest directly in an index. Any index referred to herein is the intellectual property (including registered trademarks) of the applicable licensor. Any product based on an index is in no way sponsored, endorsed, sold, or promoted by the applicable licensor and it shall not have any liability with respect thereto.
This material is not a product of Morgan Stanley’s Research Department and should not be regarded as a research material or a recommendation.
The Firm has not authorized financial intermediaries to use and to distribute this material unless such use and distribution is made in accordance with applicable law and regulation. Additionally, financial intermediaries are required to satisfy themselves that the information in this material is appropriate for any person to whom they provide this material in view of that person’s circumstances and purpose. The Firm shall not be liable for, and accepts no liability for, the use or misuse of this material by any such financial intermediary.
This material may be translated into other languages. Where such a translation is made this English version remains definitive. If there are any discrepancies between the English version and any version of this material in another language, the English version shall prevail.
The whole or any part of this material may not be directly or indirectly reproduced, copied, modified, used to create a derivative work, performed, displayed, published, posted, licensed, framed, distributed, or transmitted or any of its contents disclosed to third parties without the Firm’s express written consent. This material may not be linked to unless such hyperlink is for personal and non-commercial use. All information contained herein is proprietary and is protected under copyright and other applicable law.
Eaton Vance is part of Morgan Stanley Investment Management. Morgan Stanley Investment Management is the asset management division of Morgan Stanley.
DISTRIBUTION
This material is only intended for and will only be distributed to persons resident in jurisdictions where such distribution or availability would not be contrary to local laws or regulations.
MSIM, the asset management division of Morgan Stanley (NYSE: MS), and its affiliates have arrangements in place to market each other’s products and services. Each MSIM affiliate is regulated as appropriate in the jurisdiction it operates. MSIM’s affiliates are: Calvert Research and Management, Eaton Vance Management, Parametric Portfolio Associates LLC, Parametric SAS, and Atlanta Capital Management LLC.
This material has been issued by any one or more of the following entities:
EMEA:
This material is for Professional Clients/Accredited Investors only.
In the EU, MSIM materials are issued by MSIM Fund Management (Ireland) Limited (“FMIL”). FMIL is regulated by the Central Bank of Ireland and is incorporated in Ireland as a private company limited by shares with company registration number 616661 and has its registered address at 24-26 City Quay, Dublin 2, DO2 NY19, Ireland.
Outside the EU, MSIM materials are issued by Morgan Stanley Investment Management Limited (MSIM Ltd) is authorised and regulated by the Financial Conduct Authority. Registered in England. Registered No. 1981121. Registered Office: 25 Cabot Square, Canary Wharf, London E14 4QA.
In Switzerland, MSIM materials are issued by Morgan Stanley & Co. International plc, London (Zurich Branch) Authorised and regulated by the Eidgenössische Finanzmarktaufsicht ("FINMA"). Registered Office: Beethovenstrasse 33, 8002 Zurich, Switzerland.
Italy: MSIM FMIL (Milan Branch), (Sede Secondaria di Milano) Palazzo Serbelloni Corso Venezia, 16 20121 Milano, Italy. The Netherlands: MSIM FMIL (Amsterdam Branch), Rembrandt Tower, 11th Floor Amstelplein 1 1096HA, Netherlands. France: MSIM FMIL (Paris Branch), 61 rue de Monceau 75008 Paris, France. Spain: MSIM FMIL (Madrid Branch), Calle Serrano 55, 28006, Madrid, Spain. Germany: MSIM FMIL Frankfurt Branch, Große Gallusstraße 18, 60312 Frankfurt am Main, Germany (Gattung: Zweigniederlassung (FDI) gem. § 53b KWG). Denmark: MSIM FMIL (Copenhagen Branch), Gorrissen Federspiel, Axel Towers, Axeltorv2, 1609 Copenhagen V, Denmark.
MIDDLE EAST
Dubai International Financial Centre: This information does not constitute or form part of any offer to issue or sell, , any investment products in the UAE (including the Dubai International Financial Centre and the Abu Dhabi Global Market) and accordingly should not be construed as such. The content of this report has not been approved by or filed with the UAE Central Bank, the Dubai Financial Services Authority, the UAE Securities and Commodities Authority or the Financial Services Regulatory Authority.
Abu Dhabi Global Market (“ADGM”): This material is sent strictly within the context of, and constitutes, an Exempt Communication. This material relates to (strategy) which is not subject to any form of regulation or approval by the Financial Services Regulatory Authority of the Abu Dhabi Global Market (the “FSRA”).
Saudi Arabia: This financial promotion was issued and approved for use in Saudi Arabia by Morgan Stanley Saudi Arabia, Al Rashid Tower, Kings Sand Street, Riyadh, Saudi Arabia, authorized and regulated by the Capital Market Authority license number 06044-37.
US
NOT FDIC INSURED | OFFER NO BANK GUARANTEE | MAY LOSE VALUE | NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY | NOT A DEPOSIT
Latin America (Brazil, Chile Colombia, Mexico, Peru, and Uruguay)
This material is for use with an institutional investor or a qualified investor only. All information contained herein is confidential and is for the exclusive use and review of the intended addressee and may not be passed on to any third party. This material is provided for informational purposes only and does not constitute a public offering, solicitation, or recommendation to buy or sell for any product, service, security and/or strategy. A decision to invest should only be made after reading the strategy documentation and conducting in-depth and independent due diligence.
ASIA PACIFIC
Hong Kong: This document has been issued by Morgan Stanley Asia Limited, CE No. AAD291, for use in Hong Kong and shall only be made available to “professional investors” as defined under the Securities and Futures Ordinance of Hong Kong (Cap 571). The contents of this document have not been reviewed nor approved by any regulatory authority including the Securities and Futures Commission in Hong Kong. Accordingly, save where an exemption is available under the relevant law, this document shall not be issued, circulated, distributed, directed at, or made available to, the public in Hong Kong.
Singapore This material is disseminated in Singapore by Morgan Stanley Investment Management Company, Registration No. 199002743C. This material should not be considered to be the subject of an invitation for subscription or purchase, whether directly or indirectly, to the public or any member of the public in Singapore other than (i) to an institutional investor under section 304 of the Securities and Futures Act, Chapter 289 of Singapore (“SFA”), (ii) to a “relevant person” (which includes an accredited investor) pursuant to section 305 of the SFA, and such distribution is in accordance with the conditions specified in section 305 of the SFA; or (iii) otherwise pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. This material has not been reviewed by the Monetary Authority of Singapore.
Australia: This material is provided by Morgan Stanley Investment Management (Australia) Pty Ltd ABN 22122040037, AFSL No. 314182 and its affiliates and does not constitute an offer of interests. Morgan Stanley Investment Management (Australia) Pty Limited arranges for MSIM affiliates to provide financial services to Australian wholesale clients. This material will not be lodged with the Australian Securities and Investments Commission.
Japan:
For professional investors, this material is circulated or distributed solely for informational purposes. For non-professional investors, this material is provided in connection with Morgan Stanley Investment Management (Japan) Co., Ltd. (“MSIMJ”)’s business with respect to discretionary investment management agreements (“IMA”) and investment advisory agreements (“IAA”). This does not constitute a recommendation or solicitation of transactions nor offers any particular financial instruments. Under an IMA, with respect to the management of client assets, the client prescribes basic management policies in advance and commissions MSIMJ to make all investment decisions based on an analysis of the value, etc. of the securities, and MSIMJ accepts such commission. The client shall delegate to MSIMJ the authorities necessary to make such investment decisions. MSIMJ exercises these delegated authorities accordingly, and the client shall not make individual instructions. All investment profits and losses belong to the clients; principal is not guaranteed. Please consider the investment objectives and nature of risks before investing. As an investment advisory fee for an IAA or an IMA, the amount of assets subject to the contract multiplied by a certain rate (the upper limit is 2.20% per annum (including tax)) shall be incurred in proportion to the contract period. For some strategies, a contingency fee may be incurred in addition to the fee mentioned above. Indirect charges also may be incurred, such as brokerage commissions for underlying securities. Since these charges and expenses vary by contract and other factors, MSIMJ cannot present the rates, upper limits, etc. in advance. All clients should read thoroughly the Documents Provided Prior to the Conclusion of a Contract carefully before executing an agreement. This material is distributed in Japan by MSIMJ, Registered No. 410 (Director of Kanto Regional Finance Bureau (Financial Instruments Firms)), Membership: the Japan Securities Dealers Association, the Investment Management Association of Japan and the Type II Financial Instruments Firms Association.


